
An energy audit can reveal where a manufacturing company wastes energy, but identifying an opportunity is not the same as making an investment. For small and medium-sized enterprises (SMEs), the difficult part often begins after the audit: deciding which recommendations deserve priority, calculating their real business value and finding the resources to implement them. A technically sound proposal can remain untouched for years if it does not fit production schedules, financial constraints or management priorities.
Turning energy audits into investment requires more than a list of potential savings. It means translating technical findings into a credible business case, with realistic costs, operational benefits, responsibilities and a clear implementation plan. For industrial SMEs, this connection between energy performance and business decisions is essential to making efficiency improvements part of everyday operations rather than an occasional compliance exercise.
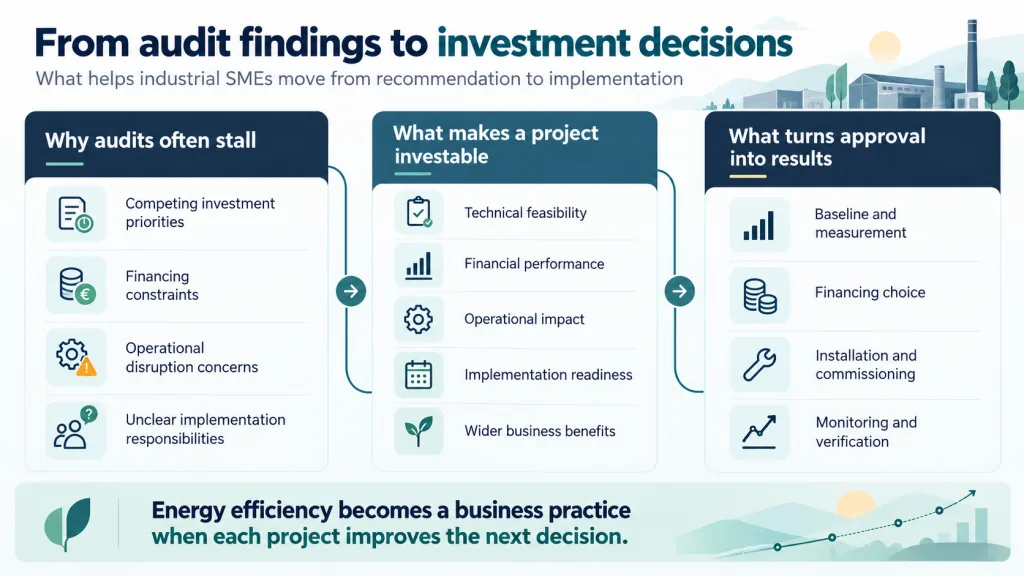
Why energy audits do not always lead to investment
An energy audit is a structured assessment of how an organisation uses energy and where consumption could be reduced. In a manufacturing business, it may examine heating and cooling systems, compressed air, motors, production equipment, process temperatures and operating practices. The findings typically identify improvement measures, estimate potential savings and recommend actions.
Yet the existence of a recommendation does not guarantee that a company can act on it. An SME might discover that replacing an ageing compressor would reduce electricity consumption, while also facing urgent demands to maintain production capacity or replace essential machinery. Even where the energy savings appear attractive, management must weigh the investment against competing priorities, uncertainty about future energy prices and the risk of interrupting operations.
Research from the European Investment Bank on energy audits and SME investment illustrates this distinction. The analysis found that audits can help overcome information barriers and encourage investment, particularly in smaller companies, but that their beneficial effect can disappear when firms face financing constraints. Better information is valuable, but it cannot compensate for a lack of investment capacity.
This is why an effective audit should be treated as the beginning of an investment process, not its conclusion. Its value depends on whether the company can use the findings to make decisions, mobilise resources and verify improvements once measures are introduced.
From technical recommendations to a convincing business case
The first step is to distinguish between identifying energy-saving potential and evaluating a project that can realistically be delivered. An audit might recommend installing variable-speed drives, improving insulation or recovering heat from an industrial process. Before committing capital, the company needs to establish whether the proposed measure is technically compatible with its equipment, production requirements and maintenance arrangements.
Consider a food-processing SME operating a refrigeration system throughout the year. An audit identifies opportunities to improve compressor control and reduce unnecessary cooling demand. The technical recommendation may be straightforward, but management still needs to understand installation costs, expected operating savings, maintenance requirements and whether the modification can be completed without disrupting production.
A useful business case therefore brings together several dimensions:
- Technical feasibility: Will the measure deliver the required performance under actual operating conditions?
- Financial performance: What are the upfront costs, annual savings, maintenance implications and expected investment returns?
- Operational impact: Could implementation affect production continuity, product quality, safety or equipment reliability?
- Implementation readiness: Who will manage procurement, installation, commissioning and subsequent performance monitoring?
- Strategic value: Does the investment support wider business objectives, such as reducing exposure to energy-price volatility or preparing for future production requirements?
These questions matter because the cheapest measure is not necessarily the most valuable, and the project with the shortest payback is not automatically the best investment. A measure that reduces maintenance needs or improves production reliability may create substantial business value beyond its direct energy savings. Conversely, an apparently attractive efficiency improvement may be unsuitable if it introduces unacceptable operational risks.
Looking beyond energy savings: the multiple-benefits approach
Energy efficiency investments are frequently assessed using simple payback: the initial investment divided by estimated annual cost savings. This is a useful first screening tool, particularly for smaller projects, but it has important limitations. It does not fully account for the timing of cash flows, financing costs, equipment lifetime or the wider effects of a change in production processes.
The multiple-benefits approach broadens the assessment by considering how energy improvements affect the business as a whole. Depending on the measure, benefits might include reduced maintenance expenditure, better temperature control, improved working conditions, fewer production interruptions or more consistent product quality. These effects should not simply be assumed; they need to be identified, evidenced and, where possible, quantified without double-counting savings.
For example, improving the control of an industrial heating system might reduce fuel consumption while also providing more stable process temperatures. If that stability demonstrably reduces rejected products, the financial value of lower waste could be included in the investment assessment. Where the improvement is plausible but has not been measured, it is better presented as a potential additional benefit rather than a guaranteed return.
This thinking is central to the DEESME 2050 project, which built on earlier work to help SMEs connect energy management, investment decisions and longer-term decarbonisation strategies. Its 2026 policy report on SME competitiveness examines how proportionate energy-management approaches and the assessment of multiple benefits can make efficiency measures more relevant to business decisions.
The practical lesson is that energy efficiency should be evaluated alongside other operational investments, using comparable assumptions and financial criteria. This gives managers a clearer basis for deciding where limited resources can deliver the greatest overall value.
Financing energy efficiency: making projects investment-ready
Once a company has identified a technically viable measure, it must determine how to pay for it. Some improvements can be financed through existing maintenance budgets or internal capital expenditure. Others, particularly equipment replacement, industrial heat recovery or more extensive process upgrades, may require external financing or a combination of funding sources.
The challenge is not always that an investment lacks economic value. A company may have insufficient cash available, limited borrowing capacity or concerns about taking on debt while future production demand remains uncertain. Smaller projects can also be expensive for lenders to assess relative to their financial value, particularly when technical documentation and projected savings are inconsistent.
The European Commission’s guidance on private and innovative energy-efficiency financing identifies high upfront costs, fragmented investment demand, financing gaps and uncertainty over returns among the barriers to greater investment. Potential responses include dedicated lending, guarantees, technical assistance and financing arrangements that link payments to energy performance.
For an SME, the right financing structure depends on the project rather than the other way around. An equipment upgrade may be suitable for a conventional loan or leasing arrangement, while some service-based efficiency improvements could be delivered through an energy service company. In an energy performance contract, payments or guarantees may be linked to agreed performance conditions, although contractual terms, measurement methods and risk allocation require careful assessment.
Before approaching a lender or financing partner, the company should be able to explain what will be installed, why it is needed, how savings have been estimated and what happens if actual performance differs from expectations. A clear baseline, realistic cash-flow forecast and credible implementation timetable can make the proposal easier to assess. These documents also help the company itself decide whether the investment remains worthwhile under less favourable assumptions.
Why implementation planning matters as much as financing
Securing investment approval does not complete an energy-efficiency project. Installation must be coordinated with production, equipment must be commissioned correctly and staff need to understand how the modified system should operate. Without these steps, the company may fail to achieve the performance anticipated during the audit.
A practical implementation plan should assign responsibility for each stage, including procurement, installation, staff training and measurement of results. It should also establish an energy baseline that accounts for relevant factors such as production volume, operating hours, product mix or weather conditions. Otherwise, a change in energy consumption after installation may be incorrectly attributed to the improvement when it partly reflects different operating conditions.
This is particularly important in industrial settings, where energy use is closely linked to production. A factory producing fewer units may consume less energy overall without becoming more efficient per unit of output. Similarly, an investment might improve specific energy consumption while total energy demand rises because production increases.
Monitoring should therefore be designed before implementation rather than added afterwards. It provides the evidence needed to determine whether the measure has worked, investigate underperformance and support future investment decisions. For SMEs seeking to build a longer-term efficiency programme, each completed project can improve the quality of the next business case.
What European projects can teach us about moving from audits to action
European initiatives have approached the challenge from different but complementary directions. Rather than treating energy efficiency solely as an equipment problem, they have explored the organisational, financial and collaborative conditions that help businesses implement improvements.
The DEESME project focused on making energy audits, energy management and the multiple-benefits approach more accessible to SMEs. Its successor, DEESME 2050, extended that perspective towards investment preparation and longer-term climate objectives. Together, they provide a useful framework for understanding why technical recommendations need to be connected to business priorities, management capabilities and financing.
The EENOVA project explored a different dimension: improving energy efficiency across regional food-processing value chains rather than working only with individual companies. Its approach combined company-level assessments with regional cooperation and stakeholder dialogue. This matters because smaller businesses may share challenges, suppliers, infrastructure requirements or opportunities for coordinated action that are difficult to address independently.
EEIP has contributed to these initiatives through its project-specific communication, dissemination and stakeholder engagement activities, helping connect technical work with relevant industrial and policy audiences. The broader lesson from their approaches is that energy efficiency does not become implementable through better technology alone. Companies also need accessible expertise, management engagement, appropriate financing and opportunities to learn from comparable businesses.
Energy audits and EU requirements: what should SMEs know?
The regulatory context is also evolving. Under Article 11 of the revised EU Energy Efficiency Directive, energy-audit and energy-management obligations are linked to enterprises’ energy consumption rather than simply their size.
The Directive establishes an energy-audit requirement for enterprises with average annual energy consumption above 10 terajoules over the previous three years, taking all energy carriers together, unless they implement an energy management system. It also requires energy management systems for enterprises whose average annual consumption exceeds 85 terajoules. The Directive specifies a first-audit deadline of 11 October 2026 for enterprises covered by the relevant provision, with audits repeated at least every four years, while national implementing requirements must also be considered.
Importantly, the Directive connects audit recommendations with action planning. Enterprises subject to the relevant audit provision must draw up a concrete, feasible action plan identifying measures that are technically or economically feasible and submit it to management. This strengthens the connection between compliance and investment decisions, although the requirement to prepare an action plan should not be confused with an unconditional obligation to implement every recommendation.
For smaller enterprises below the mandatory thresholds, proportionate approaches may be more useful than complex assessment procedures. A targeted review of major energy-consuming equipment, combined with basic monitoring and a realistic investment plan, can provide a practical starting point. The appropriate level of analysis should reflect the company’s energy use, technical complexity and investment needs.
A practical route from audit to implementation
For an SME preparing its next energy-efficiency investment, the most useful starting point is to revisit the audit recommendations through the eyes of the people who will approve, finance and operate the proposed measures. Technical teams should work with management and finance colleagues to identify a manageable group of opportunities, test their assumptions and decide which projects are ready to proceed.
A sensible sequence is to establish the energy baseline, screen recommendations for technical feasibility, prepare financial assessments, consider operational and wider business benefits, identify funding options and assign implementation responsibilities. Projects that are not yet ready should not simply disappear from the agenda. They may need additional measurements, supplier quotations, a planned maintenance shutdown or a different financing arrangement before a decision becomes possible.
Energy efficiency becomes a continuing business practice when the results of one investment inform the next. The strongest outcome of an energy audit is therefore not necessarily the number of recommendations it produces, but the quality of the decisions it enables and the improvements that can subsequently be demonstrated.
For examples of how European projects are addressing these challenges, explore EEIP’s EU-funded project portfolio and its work on energy efficiency in industrial value chains. These initiatives illustrate how technical assessment, collaboration and investment preparation can work together to help businesses move from identifying opportunities to implementing practical changes.
